Haynes Community Credit Union Logo

Welcome Loan Officers

Haynes Community Credit Union — We're your dedicated wholesale lending partner. Register loans, access programs, and get fast answers.

Register a Loan in 3 Easy Steps

Haynes Loan Officers can register and submit loans quickly through our TPO portal.

1

Login to Portal

Access the TPO portal using your assigned credentials.

2

Complete 1003

Fill out the full Uniform Residential Loan Application (1003).

3

Upload Borrower Documentation

Submit all required docs per loan program guidelines.

TPO Portal

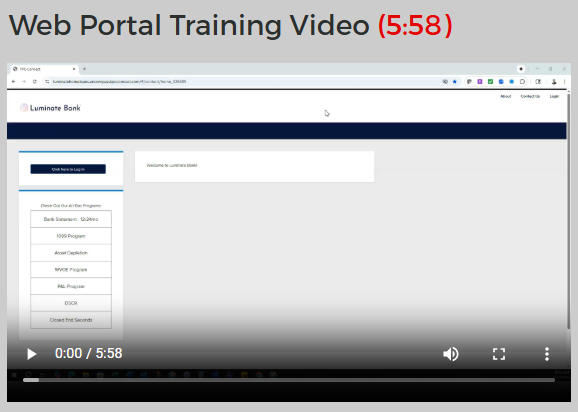
Our secure portal gives you everything you need to submit, track, and manage loans. Watch the training video to get up to speed in under 6 minutes.

Web Portal Training Video (5:58)
Web Portal Training Video

Have a Question?

Questions about loan products, unique borrower scenarios, portal issues, documentation, or loan status.

Steve DeLon

Steve DeLon

Account Executive

(765) 438-3539[email protected]
Ryan Minick

Ryan Minick

Account Executive

(765) 432-4400[email protected]
Kelly Hodges

Kelly Hodges

Loan Partner

(765) 553-4480[email protected]
Angela Kellar

Angela Kellar

Senior Loan Processor

(765) 450-8933[email protected]

FAQs

How do I register a loan in the TPO portal?

Login to Portal. Complete 1003. Upload Borrower Documentation.
What documentation is required for each loan type?

Below is a list of required documentation for each loan type. Haynes LO must upload this documentation to us through the portal. WE DO NOT ACCEPT SCREENSHOTS or PHOTOGRAPHS. *If this is all you have initially (and it will help us determine eligibility) we will take it. You will still be required to later upload acceptable documentation though.

How do I submit a Jumbo loan scenario?

JUMBO LOAN SCENARIOS SUBMIT HERE. Submit jumbo loan scenarios through the portal. Full documentation is required including all income, asset, and employment verification. Detailed letter of explanation for any credit issues is also required.

Have a Question?

Questions about loan products. Questions about unique borrower scenarios. Portal issues. Documentation questions. Loan status or changes. Give us a call Steve DeLon: (765) 438-3539 or Ryan Minick: (765) 432-4400. Email us at: [email protected].

What is the Web Portal Training?

Web Portal Training Video (5:58). Watch the training video to get up to speed in under 6 minutes.

Loan Products

What to listen for and how to guide your borrowers.

VA

Veterans Administration

To help eligible veterans, service members, and their surviving spouses purchase, build, or refinance a home.

Key Features

  • No Down Payment Required: This is the biggest advantage for most borrowers.
  • No Mortgage Insurance (MI): Unlike FHA or conventional loans with less than 20% down, VA loans do not require monthly mortgage insurance premiums.
  • Competitive Interest Rates: similar to conventional rates.
  • Limited Closing Costs: The VA limits what lenders can charge veterans in closing costs. Non-allowable fees include Processing fee, Closing/Settlement fee, Tax service fee, and Termite inspection. These can be paid by the seller (up to 4% of the loan amount) or covered/waived by the lender.
  • Assumable: In many cases, VA loans can be assumed by another eligible borrower.
  • VA Funding Fee: A one-time fee paid at closing (can be financed into the loan), though some veterans are exempt (e.g., those receiving VA disability compensation of 10% or more).

Who is it For?

  • Veterans: Those who have served a minimum period in the military (1-year active duty, 6 years Reserves or 6 years National Guard and points).
  • Active-Duty Service Members: Meeting specific service requirements.
  • Surviving Spouses: Of veterans who died in service or from a service-connected disability, and who have not remarried (or remarried after a certain age).

What to Listen For

"I served in the military... or My spouse is a veteran..."

Inquire about their service history (branch, how long, discharge status). This is the primary indicator.

"I'm looking for a low-down payment option."

VA is a good choice due to no down payment and no mortgage insurance.

"I'm currently active duty."

Active-Duty Military are eligible.

"I'm a surviving spouse of a veteran."

Determine if they meet VA eligibility requirements for surviving spouses.

"I want to avoid mortgage insurance."

If they're a veteran, the VA loan is the only government-backed option that eliminates monthly MI.

FHA

Federal Housing Administration

To make homeownership more accessible, especially for first-time homebuyers or those with lower credit scores.

Key Features

  • Low Down Payment: As low as 3.5% of the purchase price.
  • Credit Score Requirements: FHA guidelines are generally more forgiving than conventional loans.
  • Mortgage Insurance Premiums (MIP): Required for all FHA loans, consisting of an Upfront Mortgage Insurance Premium (UFMIP) and Annual Mortgage Insurance Premium (MIP). The UFMIP is usually financed into the loan.
  • Assumable: FHA loans are generally assumable.
  • Property Requirements: Properties must meet FHA minimum property standards to ensure safety, health and habitability.

Who is it For?

  • First-Time Homebuyers: A common choice due to the low-down payment.
  • Borrowers with Less-Than-Perfect Credit: FHA offers more flexibility for those with credit scores that might disqualify them from conventional loans.
  • Borrowers with Limited Savings: The low-down payment makes it easier to enter the market.

What to Listen For

"This is my first time buying a home."

FHA is often a perfect fit for first-time homebuyers due to its low-down payment and more flexible underwriting.

"My credit isn't perfect... or I had some financial challenges a few years ago."

FHA can accommodate lower credit scores (often down to 580, though lender overlays may exist for larger down payment or reserves).

"I don't have a lot saved for a down payment."

The 3.5% down payment is a significant selling point.

"I'm worried about qualifying for a mortgage."

FHA's more lenient guidelines can make homeownership a reality for a wider range of borrowers.

"I'm interested in buying a fixer upper."

While not exclusive, FHA 203(k) renovation loans can be a great option for these properties.

"I'm looking for a loan that's easy to get approved for."

While no loan is "easy," FHA's flexibility often makes it feel more accessible.

USDA

USDA Rural Housing

To promote homeownership in rural and some suburban areas by offering financing with favorable terms.

Key Features

  • No Down Payment Required: Similar to VA loans, 100% financing is available.
  • Low Mortgage Insurance (Guarantee Fee): USDA loans have an upfront guarantee fee and an annual guarantee fee, but they are generally lower than FHA's MIP.
  • Geographic Restrictions: Properties must be located in eligible rural areas. Check the USDA eligibility map: https://eligibility.sc.egov.usda.gov/eligibility/welcomeAction.do?pageAction=sfhprev
  • Income Limitations: Borrowers must meet specific income limits for the area, typically up to 115% of the median household income.
  • Competitive Interest Rates: Often very attractive.

Who is it For?

  • Borrowers in Eligible Rural Areas: This is the primary qualifier.
  • Borrowers Meeting Income Limits: Designed for low-to-moderate income individuals and families.
  • Borrowers Seeking 100% Financing: An option for those with little to no down payment.

What to Listen For

"I'm looking to buy a home in a rural area. or I'm looking at properties outside of the main city."

Immediately pull up the USDA eligibility map to check the property's location. This is the absolute first step. www.the2mg.com/haynes

"I don't have any money for a down payment."

If the property is in an eligible area and they meet income limits, USDA offers 100% financing.

"My income is moderate, and I'm looking for an affordable mortgage."

Verify their income against the USDA limits for the specific county.

Jumbo Loan Scenarios

Submit your jumbo scenarios directly to our team for fast review and pricing.

Submit Jumbo Scenario

Required Borrower Documentation

Below is a list of required documentation for each loan type. Haynes LO must upload this documentation to us through the portal.

WE DO NOT ACCEPT SCREENSHOTS or PHOTOGRAPHS

*If this is all you have initially (and it will help us determine eligibility) we will take it. You will still be required to later upload acceptable documentation though.

VA

  • Certificate of Eligibility (COE) or we can obtain via WebLGY
  • DD-214 (if separated from service)
  • LES / Paystubs for active duty
  • Tax returns / W-2s for all income sources
  • Bank statements (2 months)
  • Photo ID for all borrowers

FHA

  • Government-issued photo ID for all borrowers
  • Social Security cards for all borrowers
  • 2 years tax returns (personal & business if self-employed)
  • 2 years W-2s / 1099s
  • 30 days pay stubs / YTD profit & loss (if self-employed)
  • 2 months bank statements (all pages, all accounts)
  • Purchase agreement (if applicable)

USDA

  • Government-issued photo ID for all borrowers
  • Social Security cards for all borrowers
  • 2 years tax returns (personal & business if self-employed)
  • 2 years W-2s / 1099s
  • 30 days pay stubs / YTD profit & loss (if self-employed)
  • 2 months bank statements (all pages, all accounts)
  • Purchase agreement (if applicable)
  • Link to Property Eligibility Map verification

Jumbo

  • Full documentation package (all income, assets, employment)
  • 2 months bank statements (all pages, all accounts)
  • 2 years tax returns & W-2s / 1099s
  • 30 days pay stubs
  • Asset statements (retirement, investment accounts)
  • Purchase agreement (if applicable)
  • Detailed letter of explanation for any credit issues

Loan Program Finder

Answer a few quick questions and we'll show you the loan programs your borrowers may be eligible for.

Step 1 of 80% complete

What is your credit score?

Your middle FICO score from all three bureaus.

The 2 Mortgage Guys

Luminate Bank NMLS 1281698 Bank Headquarters 2523 S. Wayzata Blvd., Suite 100 Minneapolis, MN 55405 (952) 939-7200. This is not an offer to enter into an agreement. Information provided is outlining the minimum down payment requirements as allowed by specific loan program and product guidelines and any information, rates and programs are subject to change without prior notice and may not be available in all states. All loans are subject to credit and property approval. Luminate Bank is not affiliated with any government agency. All rights reserved.