Lafayette and West Lafayette · Tippecanoe County · Lending nationwide
Mortgage Loans in Lafayette and West Lafayette, Indiana
Ryan Minick and Steve DeLon are Branch Managers and Senior Loan Officers at Luminate Bank, working together as The 2 Mortgage Guys since 2005. Our home office is in Kokomo, about an hour from Lafayette, and we lend nationwide. Start with why people choose to live here, then we walk you through buying a home in Tippecanoe County, the mortgage options that actually fit this market, taxes and closing costs, and when USDA, renovation, or construction financing is the better tool.
Read the guide in order, or jump to the piece you need: living in Lafayette and West Lafayette, the purchase process, conventional, FHA, VA, and USDA loans, down payment assistance, renovation and construction, a payment calculator, and how we work with you. When you are ready for numbers on your file, get started or call (765) 450-8933.
Lafayette and West Lafayette are two cities across the Wabash River that live like one community, anchored by Purdue University. People move here for Purdue jobs and Purdue sports, for a historic downtown with a real main street, and for housing costs that stay well below the Indianapolis metro. Ryan and Steve work with buyers across Indiana from our Kokomo office, about an hour away, so the first question we answer is not which loan. It is whether the Lafayette area is the right place to put down roots.
You get two downtowns, a county seat, a Big Ten campus, and neighborhoods that range from historic streets near downtown Lafayette to newer subdivisions on both sides of the river and acreage out in the townships. It is a real small city market, with employers, hospitals, and schools all in the county.
Things to do
Purdue sets the calendar: football Saturdays at Ross-Ade Stadium, basketball at Mackey Arena, and concerts and lectures on campus all year. Downtown Lafayette has its own restaurants, breweries, and festivals along Main Street, and the Wabash River gives you the John T. Myers Pedestrian Bridge, the Wabash Heritage Trail, and Prophetstown State Park just outside town. Columbian Park Zoo and the Tippecanoe County Amphitheater fill in the family weekends.
Convenience
Errands stay local: grocery stores, IU Health Arnett and Franciscan Health hospitals, shopping on both sides of the river, and major employers like Purdue, Subaru of Indiana Automotive, and Caterpillar in the county. I-65 runs along the east side of Lafayette and reaches Indianapolis in about an hour, and US-231 and SR-26 connect the surrounding towns. Commutes inside Tippecanoe County are measured in minutes.
Safety
Lafayette and West Lafayette are real cities, not gated suburbs. Neighborhoods vary, from the historic districts near downtown to the quiet subdivisions families shop hardest on both sides of the river. As with any move, spend time in the neighborhood at different hours, talk to residents, and check local crime statistics to make sure it is the right fit for your family.
Schools
West Lafayette Community School Corporation serves West Lafayette and is a draw all by itself. Lafayette School Corporation covers much of Lafayette, and Tippecanoe School Corporation serves the townships and suburbs around both cities. Private and parochial options sit alongside. School preference is often the first filter on a local search, so tell us the district and we size the payment to the price band those streets actually trade in.
An hour to Indy, two hours to Chicago
Indianapolis is about an hour southeast on I-65: the international airport, the Colts, the Pacers, the Fever, and a larger job market, all close enough for a day trip. Chicago is about two hours northwest. You can work, visit family, or take a weekend trip without living inside those metros, and your mortgage payment stays a Tippecanoe County payment.
Buying a Home in Lafayette and West Lafayette
Lafayette and West Lafayette still price like a Midwest university and manufacturing market, not like a suburb of Indianapolis. That is the starting fact most out of town buyers miss. You are shopping two cities at once: historic homes near downtown Lafayette, established neighborhoods around Purdue in West Lafayette, subdivisions on both edges, and a steady mix of new construction. The Purdue calendar shapes this market, and inventory tightens in the school districts and price bands families target first.
A typical purchase still runs: conversation and pre-approval, agent search, offer, inspections, appraisal, underwriting, clear to close. In Tippecanoe County we want a licensed home inspector on almost every resale. HVAC, roof, and basement moisture are the three items that turn a pretty listing into a repair credit or a walk away, and the older housing near both downtowns can hide knob and tube wiring, unpermitted additions, or well and septic setups just outside city utilities. New construction has a different calendar: builder contract, construction draws or a one time close, and a certificate of occupancy before you move in.
Tippecanoe County also means county-level taxes, Indiana homestead timing, and title work through a local title company. None of that is mysterious, but it is not the same as buying in the Indianapolis metro. We would rather build your payment with real escrow, then have you apply, than send you out collecting quotes that ignore taxes and insurance.
Mortgage Options for Lafayette and West Lafayette Buyers
There is no single “Lafayette loan.” There is a first mortgage that matches your occupancy, credit, down payment, and the house itself. Here is how we actually sort files in this market — and what to know about each program.
Best when credit is solid and you can put 3% to 20% down. PMI is cancellable on most files once you reach the equity tests. First-time and income-limited buyers often land in HomeReady or Home Possible rather than a generic 5% product. Jumbo is less common in town but appears on larger acreage and higher end homes around West Lafayette. We walk you through credit, DTI, gift funds, and PMI so you see the full cost, not just the rate.
The workhorse for thinner credit, higher DTI, or modest down payment (typically 3.5%). FHA mortgage insurance works differently than conventional PMI — we will show you how long MIP lasts before you assume you will refinance it off in two years. FHA is also the on-ramp to 203(k) when the house needs repairs the seller will not complete. Gift funds and family help are common and documented carefully.
If you have eligible service and entitlement, VA is usually the first model we run: $0 down, no monthly PMI, residual-income test instead of a simple DTI cutoff. Funding fee rules and exemptions matter. Residual income for Indiana is a published table, not a guess. Certificate of Eligibility comes before you fall in love with a house that sits above remaining entitlement.
Zero-down guaranteed loans for eligible rural property and income-capped households. Inside the denser parts of Lafayette and West Lafayette this will not map. A few miles out it might be the cheapest cash to close story you have. Always verify the parcel. Guarantee fees are not “no mortgage insurance”; they are a different structure. We check the USDA map and household income before you write an offer.
Indiana Housing (IHCDA), Luminate PATH, Chenoa, and related seconds or grants can replace cash you do not have. They add overlays: education, income, occupancy, and sometimes a second lien you must understand before you refinance later. Assistance is not extra free money on top of an already maxed DTI; we size it with the first mortgage.
FHA 203(k), Fannie HomeStyle, Freddie CHOICERenovation, and Luminate’s interim renovation product cover different repair scopes. If you are buying a tired Lafayette house because the bones are good, we look at renovation financing instead of assuming a standard purchase will “just hold back” repair money.
Lot plus build, or build on land you already own. One-time close versus two-time close is the first decision. Payments during construction are not the same as a 30-year PITI on a finished house. We will not let you budget like they are.
First-Time Home Buyers in Lafayette and West Lafayette
Our loan process was built with first-time buyers in mind! In Lafayette that usually means a conversation about your credit, income and assets, moving on to a secure loan application to provide us the fine print, and then a face-to-face meeting to review the home buying process, housing market, interest rate strategy and home financing options. All designed to make you comfortable with your options and moving forward with a winning game plan!
Low-down conventional (3%) and FHA (3.5%) are the default comparison. VA and USDA, when they fit, can beat both on cash to close. Education is not optional window dressing: HomeReady, Home Possible, and several assistance seconds require an approved course before closing. We point you to Home Buyer Education so you take Fannie Mae HomeView or Freddie Mac CreditSmart once, the right way, instead of paying twice for a class an underwriter will reject.
For a Lafayette purchase, we also walk you through local taxes, USDA eligibility around town, and which assistance programs you can actually use here. You can learn more on our First Time Homebuyer page.
What we need from you early
Photo ID and two years of work history in plain English
Indiana property tax is assessed at the parcel, billed by the county, and often escrowed by your mortgage servicer. Tippecanoe County is not a flat “one rate for Lafayette.” Taxing districts differ between the city and surrounding townships. Assessed value is not the same as purchase price, especially in a rising or falling market, and it can lag a recent sale.
Owner-occupants should plan around the homestead standard deduction and, when eligible, the supplemental homestead deduction. Those filings typically happen after you close and occupy — they are not a lender form we submit with the 1003. Until homestead is on the tax record, an escrow estimate may look high relative to what a long-time owner pays next door. That is a timing issue, not a bait-and-switch.
Indiana’s circuit-breaker tax caps limit bills as a percentage of gross assessed value (with different caps for homestead, other residential, and other property). We mention that so you understand why two similar houses can still produce different bills. We will not invent a round-number millage for “average Lafayette.” Your title commitment, last tax statement, and the auditor’s parcel record are the source of truth. New construction can have a dramatic first-year versus second-year pattern; budget with a cushion.
Taxes plus homeowners insurance plus any HOA equal the rest of PITI. If you only compare principal and interest quotes from two lenders, you are not comparing the payment you will actually write each month. Use the mortgage calculator below with a conservative tax percentage, then let us replace that guess with the parcel’s history when you are under contract.
Tippecanoe County property lookup
The county’s Beacon map is the public record for a Lafayette, West Lafayette, or Tippecanoe County parcel: owner of record, assessed value, tax history, legal description, and sales history. Pull the parcel before you write an offer or lock an escrow estimate, then send us the address and we will reconcile it against the quote.
Cash to close is down payment plus closing costs minus credits. Tippecanoe County closings include the same buckets you see statewide, priced by the actual title company, appraisal panel, and prepaid items — not by a national blog’s “2% to 5%” slogan.
Lender items
Origination charges (how we are paid is disclosed), underwriting, processing, credit report, flood cert, and lock-related fees if any. We disclose on the Loan Estimate. Compare apples to apples: a “no origination” quote can hide a worse rate.
Title and government
Owner’s and lender’s title, search, closing fee, recording, and Indiana transfer items as they apply to the contract. The seller often pays some title pieces by local custom; your purchase agreement controls, not custom alone.
Prepaids and escrow
Per diem interest, first year of homeowners insurance, and several months of tax and insurance into escrow. This is why two identical rates produce different checks at the table.
Credits that actually help
Seller concessions within program caps, lender credits in exchange for rate, and Brighter Closing when you qualify for that client benefit. Read Closing Costs and seller-paid cost rules before you write a concession into an offer you cannot support.
Down Payment Assistance Available to Lafayette and West Lafayette Buyers
Lafayette buyers use Indiana-administered products and Luminate / national partners. Availability depends on income, first-time status, credit, property type, and whether you will occupy the home. We match you to the product you actually fit — stacking the wrong second lien is how people get stuck at refinance time.
USDA is a geography product first and a credit product second. Lafayette and West Lafayette, as denser urbanized areas, contain large stretches that the USDA map treats as ineligible. Drive a few miles into township land, neighboring small towns, or adjacent counties and the map often flips.
If the property is eligible, household income must sit under the limit for the county and household size. USDA counts adult household members in ways that surprise people who only look at the borrowers on the note. Occupancy is owner-occupied primary residence. Guarantee fees apply. Property condition still has to pass; a cheap rural house with no heat is not a USDA win.
Screenshot the USDA eligibility result, or just text the street. If it fails, we switch the same income file to FHA or conventional without making you start over.
Several well known home builders are active in Lafayette and West Lafayette, Indiana, from community builders putting up whole neighborhoods to custom builders on individual lots. The names buyers run into most often include Tempest Homes, Arbor Homes, Silverthorne Homes, Estridge Homes, and Citation Homes.
How you finance the house depends on the builder. Some will finance the build themselves, and you close a typical purchase mortgage once the home is complete. Custom builders often require a one-time close or two-time close construction loan to fund the construction phase. Learn more about our Construction Loans, including one-time close and two-time close.
Buying a Fixer-Upper in Lafayette and West Lafayette
Not every home is move-in ready. Plenty of Lafayette listings, especially in the older in town neighborhoods, need work before you can live in them the way you want.
With traditional financing, you are only allowed to borrow the sales price or the appraised value — whichever is lowest — minus the down payment requirement. That as-is cap is why a standard purchase loan will not cover the extra cost of repairs.
If you want to buy a home that needs some TLC, we have a variety of renovation loans that allow you to finance more than the sales price. Start with Renovation Loans, including FHA 203(k) and Fannie Mae HomeStyle.
Mortgage Calculator
Estimate principal, interest, tax escrow, insurance, and PMI. Defaults are a starting price band and a conservative tax line, not a quote. For side-by-side tools and a qualifier calculator, open Loan Calculators.
$
5% · $11,000
%
%/yr
$/yr
$/mo
Estimated monthly payment
$1,681
Principal & interest$1,321
Property tax$156
Home insurance$117
PMI$87
Loan amount$209,000
Current Lafayette Housing Market
Tippecanoe County
Daily Mortgage and Real Estate Video
Our daily video on mortgage rates and the Lafayette and West Lafayette housing market, updated every weekday.
Our daily Lafayette and West Lafayette mortgage and real estate video is coming soon.
Anchored by Purdue University
A university market, steady all year
Purdue University anchors the Lafayette and West Lafayette housing market. Faculty, staff, graduate students, and university families create demand in every season, not just the spring market, and neighborhoods near campus in West Lafayette behave differently from the rest of the county. For current median prices and market comparisons, see the Lafayette market data on Realtor.com, the West Lafayette market data on Realtor.com, and the Indiana Association of Realtors market reports. Market conditions shift, so check current local MLS data for the latest figures.
Two cities, one housing market
Lafayette and West Lafayette together
The Wabash River separates the two cities, but buyers shop them as one market. Lafayette offers the historic downtown, the older neighborhoods, and the county seat. West Lafayette offers Purdue and the neighborhoods around it. Many buyers tour both sides of the river in the same weekend. For current local figures, see the Lafayette market data on Realtor.com.
Lafayette and Indianapolis Inventory Trends
Regional comparison
Tippecanoe County prices generally sit below the Indianapolis metro, which keeps the area on the list for buyers relocating for Purdue, manufacturing, and logistics work along I-65. Inventory in the historic in town neighborhoods differs from the new subdivisions growing on the edges of both cities. For current inventory data, check Realtor.com and the Indiana Association of Realtors.
Lafayette and West Lafayette Homebuyer FAQs
Straight answers first, then how the process works, a Lafayette example, and what to watch for.
Can I buy a home in Lafayette with a small down payment?
Quick answer
Yes. Many Lafayette purchases close with 3% to 3.5% down on conventional or FHA financing, and some borrowers use VA or USDA with no down payment when they qualify. Down payment assistance can cover part or all of the cash due at closing if income, occupancy, and education rules are met. The right mix depends on credit, debt ratios, property type, and whether the home is inside or outside USDA-eligible geography.
How it works
We start with a full credit and income picture, then match you to a first lien (conventional, FHA, VA, or USDA) and, when it helps, a second-lien or grant program. Conventional 3% options such as HomeReady and Home Possible have income limits and education requirements. FHA uses a 3.5% minimum for most purchase files and allows gift funds. VA and USDA can be 100% financing for eligible borrowers and properties. Assistance is layered after the first lien is chosen, not before.
Example
A first time buyer targeting a modest home near downtown Lafayette or in an established West Lafayette neighborhood might combine a 3% conventional loan with Luminate PATH or another eligible assistance product if household income fits the current chart. A veteran buying the same price point might skip the second lien entirely and use VA. Someone buying just outside the cities on a USDA eligible parcel might use zero down USDA instead of FHA. We run those three files side by side so you see cash to close and monthly payment, not just the advertised down payment percent.
Important exceptions
Manufactured homes, condos, and two-to-four unit properties follow extra rules. Investment purchases do not get the same low-down occupancy programs. USDA is property- and income-limited. Some assistance cannot be combined. Gift funds are welcome on many programs but must be sourced and seasoned correctly. If credit events are recent, FHA or a manual underwrite may be the path even when 3% conventional looks cheaper on paper.
Ryan & Steve’s take
Do not pick a program because a neighbor used it last year. Local inventory includes everything from historic homes near downtown to new construction on the edge of Tippecanoe County, and the loan that fits one house will fail on another. Bring us the address and we will tell you which down-payment story is actually available.
Official guidelines / sources
Fannie Mae Selling Guide (HomeReady / standard conventional LTV), Freddie Mac Home Possible, HUD Handbook 4000.1 (FHA minimum investment), VA Lenders Handbook, USDA HB-1-3555, IHCDA / Hoosier Homes program guides, and Luminate PATH product overlays.
Does living in Lafayette or West Lafayette city limits disqualify USDA financing?
Quick answer
Often, yes for addresses inside the incorporated city — and often no a few miles out. USDA Rural Development eligibility is mapped by census tract, not by “Tippecanoe County” as a whole. The denser neighborhoods in Lafayette and West Lafayette are typically ineligible. Many properties in surrounding townships and neighboring counties remain eligible. You verify the exact parcel on USDA’s map before you write an offer, not after inspection.
How it works
We check the street address against the current USDA eligibility map, then check household income against the county limit (which counts more than W-2 wages). Occupancy must be primary residence. The home must meet USDA property standards, which can be stricter on repairs than a conventional appraisal. Guarantee fees are financed or paid in cash according to the product. If the house is ineligible, we pivot to FHA, conventional, or VA without restarting your file from scratch.
Example
A buyer touring a home near downtown Lafayette or near the Purdue campus should assume USDA is off the table until the map says otherwise. The same buyer looking at acreage toward Dayton, Battle Ground, or the rural edges of Tippecanoe, Warren, or Fountain counties should have USDA on the comparison sheet. Eligibility can change when census updates hit the map, so we re-check even if a similar house qualified last year.
Important exceptions
Income limits are household-based, not just borrower-based. Existing USDA borrowers refinancing follow different geography rules than new purchases. Properties with income-producing land, incomplete construction, or significant deferred maintenance can fail even in an eligible zip code. If you already own a home, remaining occupancy and property disposal rules apply.
Ryan & Steve’s take
Never let a listing agent tell you “this area is USDA” without a map screenshot. We pull it the same day you send the address. If USDA dies, FHA or a 3% conventional plus assistance is usually the backup for Lafayette buyers — not a dead deal.
Official guidelines / sources
USDA Rural Development Single Family Housing Guaranteed Loan Program (HB-1-3555) and the USDA property eligibility site. Income limits are published by USDA and change; we use the chart in force at underwriting, not a blog post.
How do Tippecanoe County property taxes affect my mortgage payment?
Quick answer
Your monthly principal-and-interest is only part of the payment. Most Lafayette loans escrow property tax and homeowners insurance, so the tax bill is spread across twelve months. Indiana’s homestead standard deduction (and supplemental homestead, when you qualify) can lower the taxable assessed value for an owner-occupant. Exact millage still varies by taxing district — Lafayette or West Lafayette versus a township — and by assessed value. We estimate; the county issues the bill.
How it works
The lender’s underwriter uses assessed value, last known tax amount, and local factors to set the escrow. After you close and file for homestead (typically through the county auditor after you occupy), later tax bills may drop if you were estimated without that deduction. That can create an escrow surplus or shortage at analysis. New construction and recent purchases sometimes have a “first year” tax that does not match the long-run bill.
Example
Two houses with the same sale price can escrow different tax amounts if one sits in a different taxing unit or has a different assessed-value history. A buyer coming from Indianapolis often notices Tippecanoe County’s overall housing cost is lower; that does not mean their first escrow analysis will match the listing flyer. We would rather over-explain the range than surprise you at month two.
Important exceptions
Homestead is not automatic on every file and is not available for investment properties. Tax caps (circuit breaker) in Indiana limit bills as a percent of gross assessed value, but the details are statutory and parcel-specific. Special assessments, ditch assessments, or unpaid prior-owner amounts can appear on a title commitment. Always read the commitment; do not rely on Zillow tax figures.
Ryan & Steve’s take
Ask us for a payment that includes a conservative tax line, then confirm the parcel with your title company and the Tippecanoe County Treasurer / Auditor resources. If you are moving from a high-tax metro, the monthly number still needs to be built from this county’s bill, not from a national average.
Official guidelines / sources
Indiana Department of Local Government Finance homestead deduction materials, Tippecanoe County Auditor / Treasurer billing practices, and CFPB escrow account rules. Tax amounts are public record for a given parcel; we do not publish a single “Lafayette tax rate” because it would be misleading.
Should I get pre-approved before I tour Lafayette listings?
Quick answer
Yes. Tippecanoe County Realtors and listing agents expect a current pre-approval before they treat an offer as serious, especially when inventory is thin in a price band. Pre-approval is a credit, income, and asset review — not a rate lock and not a guarantee until the property appraises and underwriting clears. It also tells us which program family to use so you do not write an offer on a house your loan cannot close.
How it works
You complete an application, we pull credit (with your authorization), gather income docs, and issue a letter that states a max purchase price and loan type. When you find a house, we update the letter to that address, order the appraisal after contract, and move through processing with Angela and the team. Rate locks are a separate conversation tied to contract timing.
Example
A buyer who shops first and applies later often loses a weekend of negotiations. A buyer who is pre-approved can write with a realistic ceiling, know whether USDA is even possible, and avoid offering on a manufactured home that will not meet the program they assumed.
Important exceptions
Self-employed, commissioned, or recently job-changed borrowers need a deeper income review; a same-day letter may be a pre-qualification until tax returns are in. Condos and new construction have extra approval steps. A pre-approval expires; we refresh it when you are actively writing offers.
Ryan & Steve’s take
Call or apply online before you spend Saturday on showings. We would rather spend thirty minutes on your file than watch you fall in love with a house your debt ratio cannot support.
Official guidelines / sources
Ability-to-Repay / QM rules, Fannie Mae and FHA documentation standards, and Indiana purchase-contract custom that sellers request lender letters with offers.
Can I buy a fixer-upper in Lafayette and finance the repairs?
Quick answer
Often yes, if the work is eligible and a contractor (or, in limited cases, a qualified borrower) can complete it under the program’s draw rules. FHA 203(k) and Fannie Mae HomeStyle are the two purchase-and-renovate paths we use most. Standard FHA and conventional loans only finance the as-is house and will not hold repair money in escrow the same way. Heavy structural work, unpermitted additions, and “sweat equity” plans need an honest scope before you bid.
How it works
We review the property, the repair list, and your credit. Limited 203(k) fits smaller, non-structural jobs under HUD’s cap. Standard 203(k) uses a HUD consultant and supports more extensive rehab. HomeStyle can finance luxury-level finishes conventional buyers want, with different LTV and contractor rules. After closing, funds are held and released as work is inspected. You typically cannot live in an uninhabitable house during a full gut unless the program and consultant allow it.
Example
A dated Lafayette ranch that needs HVAC, roof, and kitchen may fit Limited 203(k) or HomeStyle depending on cost. A house with foundation, electrical, and layout changes is Standard 203(k) territory. If the seller will not wait for a renovation underwrite, a conventional purchase plus a later HELOC is a different (and often weaker) plan — we will say so.
Important exceptions
Investors have fewer 203(k) options. Manufactured homes and condos have tight renovation overlays. DIY is restricted. Cost overruns need a contingency; if the bid is fantasy, the loan dies in underwriting, not at the punch list.
Ryan & Steve’s take
Walk the house with a contractor before you fall in love with the after-photos in your head. Send us the bid. We will tell you 203(k) versus HomeStyle versus “this is a cash rehab, not a mortgage rehab.”
Official guidelines / sources
HUD 203(k) handbook and mortgagee letters, Fannie Mae HomeStyle Renovation Selling Guide, and our renovation overlays at Luminate Bank.
You will work with a local team, not a remote call center. Ryan Minick grew up in Peru, moved to Kokomo in 2001, raised his family here, and has been in mortgage origination since 2003. Steve DeLon has been helping people understand the loan process since 2000 and still works files the way a local Branch Manager & Senior Loan Officer should: on the phone, in the office, and in the details. Together, Ryan and Steve have won Honor Affiliate of the Year from the Realtors Association of Central Indiana four times collectively. Learn more on Meet The Team.
You’ll be working with a local team that knows the market, the realtors, appraiser, title companies, and the housing market. We live and work here, and are actively doing our part to make Kokomo the best community around!
City of Kokomo’s Community Cornerstone Award
State of Indiana’s Hardworking Hoosiers Award
4-time Affiliate of the Year recipients with RACI
Kokomo Downtown Champions
2025 Small Business of the Month (Greater Kokomo Chamber)
11 years of supporting Bridges Outreach with Hawgin’ the Block
Co-creators of downtown’s First Fridays
The 2 Mortgage Guys are local people powered by a national bank with a full shelf of loan products, lending nationwide. If that is the experience you want, Get Started and we will put a real plan on your file.
Kokomo Office
1221 Appletree Lane Kokomo, IN 46902
Hours: Monday – Friday, 8:30 AM – 5:00 PM. Evenings and weekends by appointment.
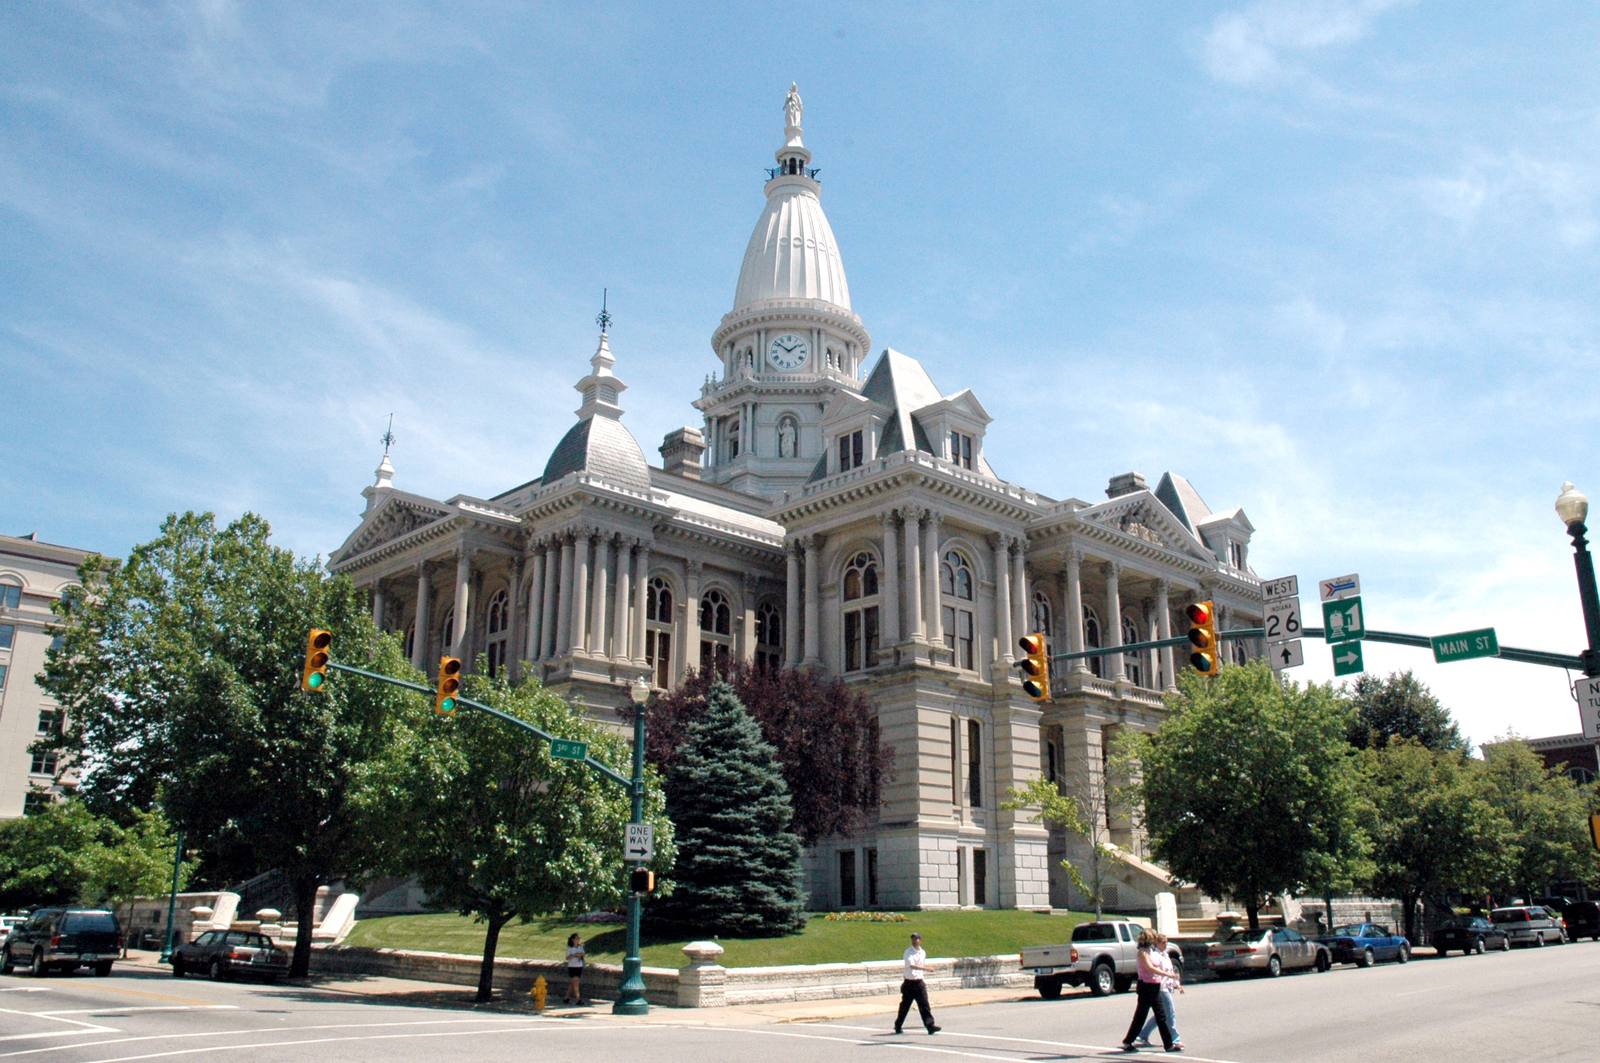
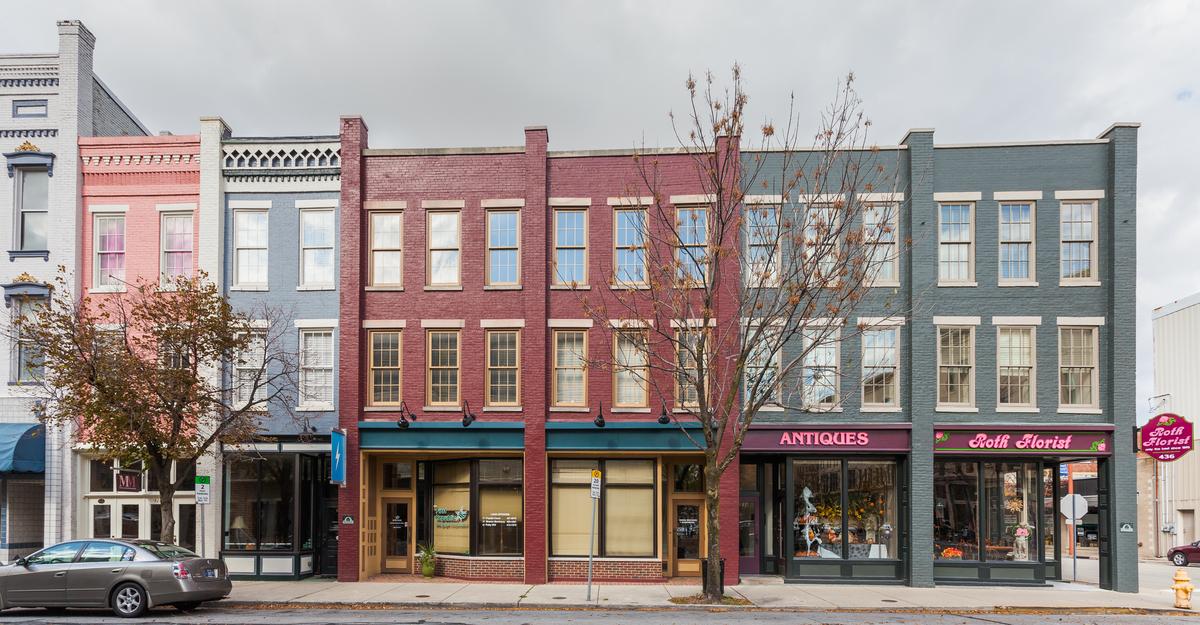
Photos: Tippecanoe County Courthouse photo by Blross, public domain, via Wikimedia Commons. Main Street photo by Diego Delso, CC BY-SA 3.0, via Wikimedia Commons.
Ready to get pre-approved?
See how the loan programs, process, and payment tools fit your situation. Apply when you want a letter you can write offers with.